Private Capital / Readiness
Ready to Raise
Private Capital?
A successful capital raise begins before the first investor conversation.
This assessment evaluates areas that commonly affect private offering execution:
1. business foundation
2. offering architecture
3. investor strategy
4. execution readiness
~5 MINUTES · 20 QUESTIONS
The Private capital engagement
How it Works
Raising Private Capital is a Regulated Securities Transaction
It's not simply a fundraising campaign, even if it's just "a small round" or "friends and family"
Our focus is helping issuers approach the market with a transaction that has been structured deliberately before investors are asked to commit capital.
01
Assess
Clarify the business, target investors, timeline and strategy.
02
Structure
Choose the issuing entity, security, economics and exemption architecture.
03
Document
Build the offering materials and subscription process around the deal.
04
Prepare
Coordinate approvals, diligence responses and filing readiness.
05
Launch
Move into the offering process with defined next steps.
Legal Counsel for the Raise. Not an Investor Introduction Service.
A clear boundary for an ethical client centric legal representation.
RAETZER provides legal counsel and negotiation for the structure, documentation and execution of a private capital raise. We do not find investors, broker securities, market offerings or promise access to a particular investor network.
That distinction helps keep the engagement legally and ethically focused. If you have a plan to reach prospective investors, we can stucture the legal architecture for the conversation to take you from pitch deck to wired funds.
The next decision
Ready to
Raise?
Start with a structured screening of the business foundation, offering architecture, investor strategy and execution readiness.
PRIVATE CAPITAL RAISE PACKAGE ESTIMATES
Company Formation / Clean Up → Offering Structure → Draft Offering Suite → Investor Outreach → Subscriptions → Funding → Closing → Ongoing Obligations
A private offering is a securities transaction, not merely a document project. These packages cover defined legal work for qualifying offerings.
All matters are billed on an hourly basis (estimate amount is not paid upfront).
RAETZER does not guarantee capital will be raised and does not provide investor introductions or placement agent services.
Package 1
PRIVATE OFFERING ESSENTIALS
Rule 506b — U.S. Accredited Investors Only
$14,500
Starting at; Final fee ESTIMATE confirmed after attorney review.
Best for
a qualifying U.S. company privately raising capital from existing substantive business and investor relationships without public advertising or general solicitation.
Principal inclusions
Offering-structure and Rule 506b analysis
One U.S. issuer and one class or series of securities
Private Placement Memorandum or agreed disclosure memorandum
Subscription agreement and accredited-investor questionnaire
Standard issuer approvals and one initial closing
Form D and coordination of up to five standard state notice filings
VIEW SCOPE AND ASSUMPTIONS
Assumptions: one U.S. issuer; one offering; one class/series; U.S. accredited investors only; no general solicitation/public advertising; no non-accredited investors; no pooled fund or complex waterfall; no prior offering remediation; no success based finder/unregistered intermediary issue; 1 initial closing; up to 2 consolidated revision rounds; up to 5 standard state Blue Sky notice filings with government fees separate; complete reasonably organized company, ownership, financial, business information. Eligibility, scope and estimate are confirmed after readiness assessment, conflicts review, attorney consultation and execution of an engagement agreement.
No guarantee any investor is accredited or any verification method suffices in every circumstance. Exclusions: investor introductions, accounting, financial-statement preparation, tax, foreign-law, broker-dealer services, Investment Company/Investment Adviser analysis, CFTC matters, litigation, and prior-securities remediation. Additional exclusions and assumptions will be listed in engagement agreement.
Package 2
GENERAL SOLICITATION OFFERING
Rule 506c — U.S. Accredited Investors Only
$19,500
Starting at; Final fee ESTIMATE confirmed after attorney review.
Best for
a qualifying U.S. issuer that intends to promote a private offering through LinkedIn, YouTube, webinars, email, advertising, or a publicly accessible landing page.
Principal inclusions
Everything included in Private Offering Essentials
Rule 506c and verification process analysis
Review of 1 pitch deck (up to 25 pages)
Review of 1 offering landing page
Review of up to 10 proposed social media posts
Review of 1 standard offering email or webinar invitation
VIEW SCOPE AND ASSUMPTIONS
Legal review of substantially complete solicitation materials only, not creation/design/writing/management/
distribution.
One initial legal review and 1 consolidated revision review of the listed materials.
Materially revised campaigns, additional ads, pages, decks, video scripts, webinars, influencer arrangements, continuing review require supplemental scope. Eligibility, scope and estimate are confirmed after readiness assessment, conflicts review, attorney consultation and execution of an engagement agreement.
No guarantee any investor is accredited or any verification method suffices in every circumstance. Exclusions: investor introductions, accounting, financial statement preparation, tax, foreign law, broker dealer services, Investment Company/Investment Adviser analysis, CFTC matters, litigation, and prior-securities remediation. Additional exclusions and assumptions will be listed in engagement agreement.
Package 3
U.S. AND INTERNATIONAL PRIVATE OFFERING
Rule 506b or Rule 506c + Regulation S
$29,500
Starting at; Final fee ESTIMATE confirmed after attorney review.
Best for
a qualifying U.S. issuer with 1 class, U.S. accredited investors, and a limited eligible non-U.S. offshore offering.
Principal inclusions
Coordinated Rule 506 and Regulation S structure
Integrated U.S. and offshore disclosure package
U.S. and non-U.S. subscription provisions
Regulation S representations, legends, transfer restrictions
Review of proposed offshore solicitation
Coordination with foreign counsel where local law advice is required
VIEW SCOPE AND ASSUMPTIONS
Assumptions and limitations: one U.S. issuer, one class/series, one integrated offering, U.S. sales under 506b/c, qualifying offshore Regulation S sales, and no more than two foreign jurisdictions for issue identification/coordination.
No foreign issuer, feeder, blocker, parallel fund, offshore vehicle, no foreign opinion or filing by RAETZER, no material foreign tax structuring; foreign counsel, tax advisers, translators, local agents, filing costs separate.
Funds, offshore vehicles, multiple classes, substantial foreign-law work, digital assets, non-accredited investors, Investment Company/Investment Adviser issues, CFTC matters, and other complex structures require custom scope and may exceed the starting price. Eligibility, scope and estimate are confirmed after readiness assessment, conflicts review, attorney consultation and execution of an engagement agreement.
No guarantee any investor is accredited or any verification method suffices in every circumstance. Exclusions: investor introductions, accounting, financial-statement preparation, tax, foreign-law, broker-dealer services, Investment Company/Investment Adviser analysis, CFTC matters, litigation, and prior-securities remediation. Additional exclusions and assumptions will be listed in engagement agreement.
A transaction process, not a shortcut
Regulation D Does Not Eliminate Securities Law Risk
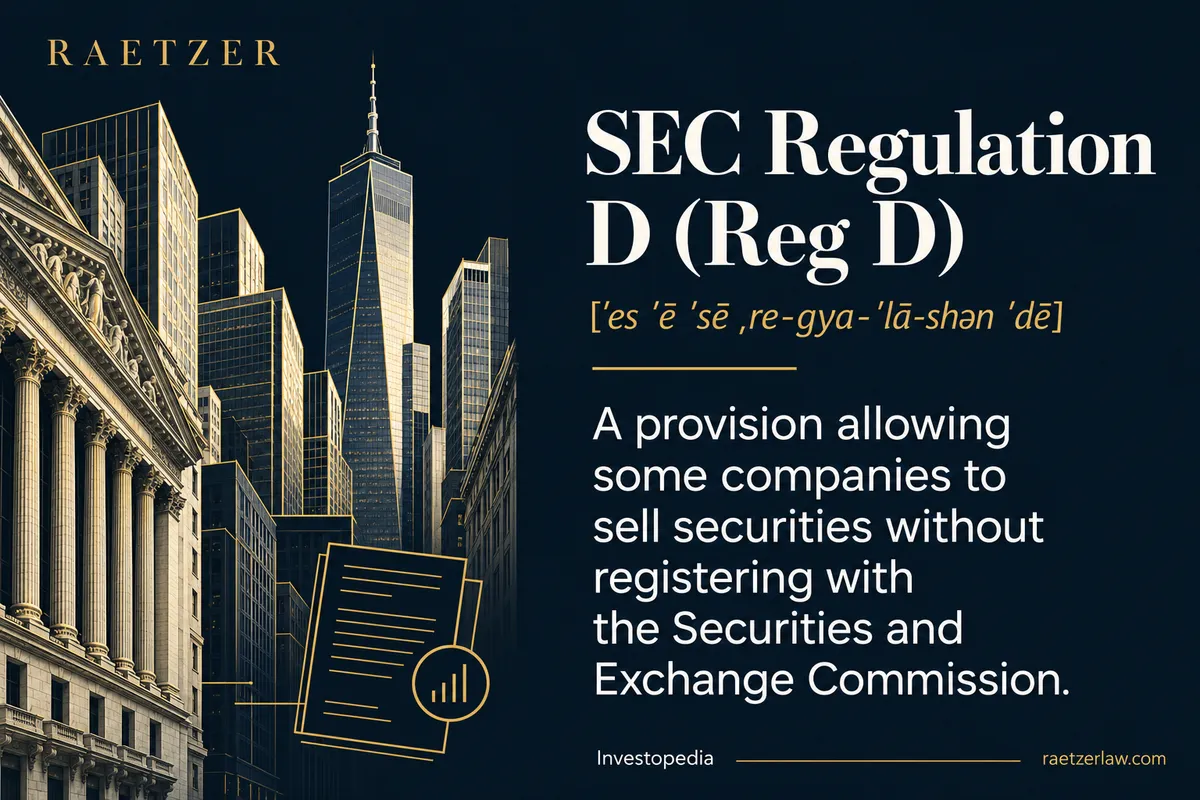
Regulation D provides exemptions from SEC registration when its requirements are satisfied. It does not eliminate the federal antifraud rules, and state notice requirements may continue to apply.
Offering structure, disclosure and communications should therefore be addressed as parts of a single transaction process.
Two common pathways
Structure the offering around the investors sought.
The exemption and the way an offering reaches investors need to work together.
Company
Offering Structure
Investors
506(b): Relationship-Based
No General Solicitation + Self Certification
506(c): General Solicitation
Permitted / Accredited Purchasers + Verification
Private Capital Raise Readiness Assessment
Start Your Assessment
RAETZER PLLC
Led by a corporate and securities lawyer with more than 20 years of transactional experience across $100+ billion in transactions, we bring institutional deal discipline to businesses that want sophisticated counsel without building an in-house legal department. Sophisticated counsel for the decisions that move a business forward — from first formation through its next chapter.
Office MAILING ADDRESSES
224 W 35th St, Suite 500 #2320
New York, NY 10001
1910 Pacific Ave
Suite 2000 #1625
Dallas, TX 75201
2026 © All rights reserved. RAETZER PLLC.
The materials on this website are provided by RAETZER PLLC for general informational and educational purposes only. They are not intended as legal advice, do not constitute legal advice, and should not be relied upon as legal advice for any particular matter or situation. Viewing this website, using this website, submitting information through this website, or communicating with RAETZER PLLC through this website does not create an attorney-client relationship. An attorney-client relationship is formed only after RAETZER PLLC has agreed in writing to represent you. Do not send confidential, privileged, or time-sensitive information through this website unless and until an attorney-client relationship has been established. Information submitted before an attorney-client relationship is formed may not be treated as confidential or privileged. The information on this website may not reflect current legal developments and may be changed or updated without notice. Legal outcomes depend on the specific facts and applicable law. No statement on this website is intended to create, and no statement should be understood as creating, a guarantee, warranty, prediction, or assurance regarding the outcome of any legal matter. RAETZER PLLC does not seek to represent any person or entity in any jurisdiction where this website does not comply with applicable laws and ethical rules. Unless expressly stated otherwise, the attorneys identified on this website are not certified by the Texas Board of Legal Specialization. This website is for educational purposes only. The attorney responsible for the content of this website is Joseph J. Raetzer, MBA, JD, RAETZER PLLC.
Legal services are provided only after engagement and conflicts clearance.